tl;dr
Excluding MSTR from indices isn’t the most helpful of moves. A blow-up of BTCS because of leverage (surprise, surprise) would land a body blow.
Market Snap
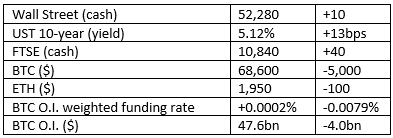
Market Wrap
I was reminded (https://americanledgerdaily.com/) that in 2025 the US federal government was shut down from October 1st to November 12th. This happens with ever more frequency as the annual deficit grows, along with the ever-increasing burden of paying interest on the ever-growing debt pile. Proponents of quantitative easing forgot to mention that bit in their enthusiasm for making paupers of generations of unborn children who will look back on us with disbelief.
That “hot” CPI number on Tuesday was based upon a yearly comparison with last October – for which, because of the shutdown, there is no data. The same for today’s PPI – it is a comparison with last October, for which there is no data.
There is talk that at the December meeting the Fed is contemplating raising short-end rates by 50bps, a move that will strip cash out of everybody’s pockets, mostly for the benefit of hedge funds.
And all based on an inflation calculation which is even more fake than usual.
There is something rotten at the heart of that setup.
Occasional Series – Stacy Keach, RIP
Putting Luther Blissett to one side (my absolute hero for all time – that pedestal will always have his name on it), as a young teenager I was entranced by two other role models, both TV characters.
Minder’s Terry McCann, played by Dennis Waterman, fascinated me by his shape-shifting, which was perfect in whatever company he found himself in. I envied that, and lauded it too, because that is beyond me in my personal life.
Stacy, as Mickey Spillane’s Mike Hammer, didn’t do that. You always knew who he was, what he would do, and how he would express himself – verbally or physically – to get what he wanted.
Do not think for one moment this made Stacy one-dimensional. Mike Hammer was just one of the many presentations of his genius.
Curious Cryptos’ Commentary – Strategy Inc. (MSTR) and MSCI Inc.
MSCI designs and maintains investment indices. These are used as benchmarks for active investment funds, and as targets for passive funds and ETFs. It provides more than 239,000 equity and fixed-income indices daily. It has reported that $2.8 trillion in equity ETFs are directly linked to its indices. In addition, nearly $23 trillion of assets are benchmarked to its indices. Rightly or wrongly, MSCI has significant clout in the passive and active investment world.
MSCI determines its own rules for each index. Some of these are principles-based – for example, factors such as the market cap, the free float, and a measure of liquidity are used to assess the suitability of all companies in an index. However, many of the rules are seemingly arbitrary.
Two days ago, MSCI released its November review which states that Strategy Inc. will be removed from its MSCI USA Index, amongst others, after the close of trading on November 30th. The reason is that it has introduced new rules that exclude companies that resemble investment funds from a broad selection of its indices.
Passive investment funds, and ETFs based upon the affected indices are forced sellers of MSTR stock before November 30th, whilst active funds have more discretion. MSTR has estimated that funds linked to MSCI indices hold just over 3% of its common stock. These won’t all come to market immediately, but over the next couple of months that will be a source of ongoing selling, which has a downward impact on the stock price of MSTR. Given that MSTR’s model of selling stock to buy BTC is impacted by its share price, MSTR’s ongoing programme of buying BTC is negatively impacted by this technical change.
This isn’t the cause of BTC price weakness this week.
The spot BTC ETFs have seen outflows of over $2.5bn since 30th October, driven by fears over the AI bubble, and the strength of the dollar in expectation of yet more rate rises based upon incomplete and inaccurate inflation data. But it does add to the current, temporary, doom and gloom.
Curious Cryptos’ Commentary – BTCS
BTCS is a Digital Asset Treasury Company (DATCo) that exists to accumulate digital assets, mostly ETH in the case of BTCS.
It began by selling stock to buy ETH, which was then staked. Staking rewards would be used to pay ongoing costs with a long-term view that shareholders would be rewarded with an increase in the value of the underlying assets. For retail investors that want exposure to ETH, buying BTCS removes all custody risk, and allows ETH exposure to be held within a tax-free wrapper. The effective cost is to give up some of the staking rewards.
That is all good and is a perfectly justifiable business model.
A very bad decision would be to add leverage by borrowing against the company’s ETH holdings to then buy more ETH or other cryptos. That trade can work fine when markets are in good shape but can go horribly wrong when they are not.
The Board of BTCS decided that it could borrow up to 50% of the market value of its holdings. It has done this by depositing a “significant majority” of its digital assets on Aave (a DeFi platform) and borrowing both USDT and GHO (Aave’s stablecoin) against that collateral. I assume the USDT has been deployed in buying more ETH, which in turn has been deposited on Aave. Note that the company has very little cash on hand.
Aave, as a DeFi platform, has a simple and hard-wired calculation that liquidates any collateral held against a loan based upon some pre-determined factors. This calculation results in a “liquidation price” which is the market price of ETH at which the loans and collateral are collapsed.
For BTCS that price is currently $1,717 compared to $1,950 at the time of writing:
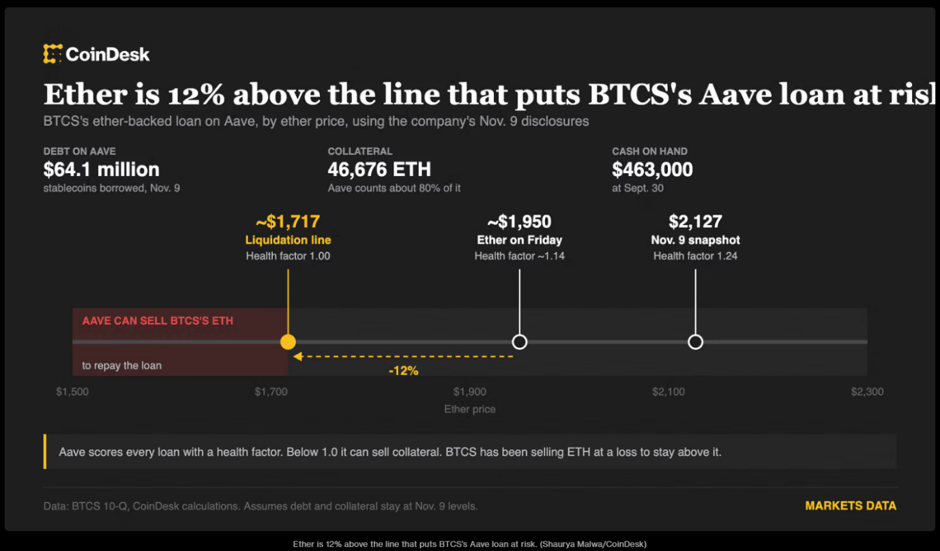
Unless BTCS can post more collateral, or pay off some of its loan, a mere 12% drop in the price of ETH will lead to wholesale liquidation, probably leaving the company with few assets. Shareholders will be nursing losses that might approach 100% of their investment.
Using leverage in the crypto world is just a dumb move every time.
Why does all this matter?
Confidence is hard to gain, and very easy to lose.
There is no doubt that the exclusion of MSTR from many major indices is a step backwards in the process of adoption of BTC as an investment asset.
A collapse of BTCS will call into question the very existence of DATCos.
The old Santa Claus rally is looking a long way off right now.